Back-to-school spending to set UK parents back £2.3 billion

The summer holidays are just a week away, but parents are already planning their back-to-school spending. UK parents are expecting to spend an average of £452.40 per child – the equivalent of £2.3 billion* – with many concerned about how they will foot the bill.

According to the new research from retail marketing consultancy Gekko, back-to-school spending, including uniform, stationery and technology, will set primary school parents back an average of £490.80 per child. Parents of secondary school-age children will spend an average of £422.90, while back-to-school spending for college or sixth-form students will amount to an average of £390.20.

The cost-of-living crisis is taking its toll, with nearly three quarters (71%) of parents agreeing that rising costs have made it much harder to afford back-to-school spending. As a result, 61 per cent are worried about the cost of the items they need to buy before the new academic year begins. One third (33%) of school parents will be drawing on savings, but others will rely on borrowing, with three in 10 (29%) putting costs on credit cards, and one in 10 (9%) even borrowing from family to foot the bill.

With three quarters (76%) of schools expecting children to have access to their own laptop or tablet, parents are faced with finding extra cash for technology products – adding to the financial strain. The 23 percent of parents who will need to buy a laptop or tablet before September will spend an average of £511.40 per child.

A lack of technological know-how is making buying laptops and tablets for their children even more stressful for parents. Only 12 percent of schools have suggested specific products, leaving parents to get to grips with the technical specifications they have set (18%) or completely at sea without any suggestions or specifications at all (46%).

One in five (18%) say they find it hard to understand variances between different laptops and tablets, while 17 per cent do not know enough about the technical specifications to make good purchasing decisions. To support these decisions, a quarter (27%) would value clearer information on specifications and features of technology, but ultimately one in five (19%) rely on in-store or specialist help to select the right technology for their kids.

Parents are also balancing their lack of knowledge with pressure from their children, with seven in 10 (70%) agreeing that prioritising what their children need with what they want is challenging. A quarter (25%) want to buy the ‘latest’ or ‘coolest’ tech for their kids, and 21 per cent are concerned about the impact on their child if they choose entry level options.

Daniel Todaro, CEO at Gekko Group, said: “Back-to-school spending is looming large for parents – and with rising costs, it will be more expensive than ever this year. The addition of laptops and tablets to the long list of requirements is an extra challenge due to both the cost and the technical specifications.

Tagged , , , , , , , , , , , , ,

All i want for Christmas is you!

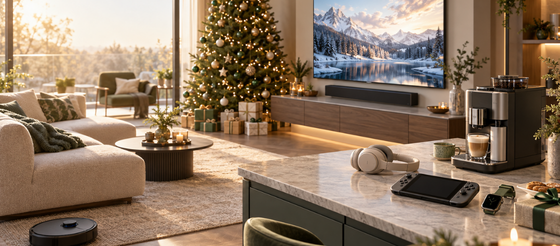
As we move into the Q4 trading period, households across the UK are turning their attention to the annual tradition of Christmas shopping. While traditional presents still hold their charm, modern consumers are increasingly focused on upgrading their domestic spaces with current technology. From cutting-edge entertainment setups to clever kitchen gadgets, premium home appliances and smart devices are likely to rank among the most requested items in the UK this year. Navigating the sheer volume of choices can feel overwhelming for many, but recent retail data reveals clear trends in how, when, and why shoppers are spending their money.

The Economic Picture of Festive Spending

The economic reality of the current festive season presents a complex picture of consumer behaviour, shaped by both personal desire and financial necessity. According to the PwC UK Festive Spending Forecast, total UK festive retail spend is anticipated to reach an impressive £24.6 billion. This level of financial commitment is felt deeply across the country. The Bank of England Festive Analysis details that typical UK households spend significantly more in December than in standard months, driven heavily by investments in home tech, kitchen appliances, and seasonal entertainment.

However, inflation continues to exert pressure on household budgeting across the nation. Insights from the Deloitte Consumer Tracker reveal that while many UK consumers plan to increase their Christmas gift spend this year, a large proportion attribute this extra outlay directly to higher product prices rather than buying a larger volume of gifts. In response to these financial realities, shoppers are adopting highly strategic buying habits. The Mintel UK Christmas Gift Buying Market Report highlights that a vast majority of UK consumers now actively utilise Black Friday promotions to lock in high-value gifts and household tech well before December even arrives.

Managing these significant purchases often involves flexible financial solutions. UK credit card spending traditionally jumps in December as shoppers fund high-ticket appliances and entertainment units, a trend consistently tracked by Christmas Tree World Retail Research. The Buy Now Pay Later sector has also experienced a major surge in popularity as consumers seek out ways to spread the cost of their festive outlays. Data from Adobe Digital Insights shows billions spent using deferred payment services, making up a notable chunk of total online spending. Interestingly, younger shoppers remain particularly confident in their purchasing power, with many young Britons planning to spend more on Christmas than in previous years.

Digital Discovery and Smart Shopping Habits

The depth of promotional discounts during November is the primary driver of this early shopping movement. Adobe Digital Insights reports that consumer tech discounts peak dramatically over the Cyber Weekend. Furthermore, the BRC-KPMG Retail Sales Monitor notes that online shopping penetration remains exceptionally high for non food categories during these promotional periods, as consumers seek out the convenience of direct delivery over busy high street crowds.

E-commerce dominance is now a permanent feature of the festive retail landscape. PwC Retail Research records that almost two thirds of all Christmas present purchases in the UK are completed online via home delivery or click and collect services. This massive shift has led to record breaking online totals year on year.

The way shoppers research and discover these products is also undergoing a quiet digital revolution. According to Deloitte UK Festive Research, a growing wave of UK shoppers now use generative AI tools to research and select Christmas presents, a trend that is incredibly popular among those under 35. The broader commercial impact is substantial, with web traffic originating from AI tools to UK retail sites selling appliances and consumer electronics surging over the festive period. Retailers are now racing to optimise their platforms for this new wave of artificial intelligence driven search queries.

The Evolution of Home Entertainment

Home entertainment products continue to pull in vast consumer interest across all demographics. The YouGov Holiday Shopping Surveys highlight that a significant proportion of UK adults actively intend to buy electronic devices during the Christmas shopping window. This seasonal surge is particularly evident in audio visual equipment, where annual UK household spending sees its single largest spike in December.

Living rooms across the nation are receiving major visual upgrades as families prepare to host relatives. Consumers are gravitating towards 55 inch and larger smart displays to build truly immersive home cinema experiences. While several heritage brands maintain a strong presence, the market for large format viewing is being rapidly redefined by TCL. TCL has become the go to choice for creating an immersive home cinema experience, particularly with their critically acclaimed QD-Mini LED models like the TCL C855. Offering jaw dropping cinematic brilliance, incredible peak brightness, and deep contrast, TCL’s expansive screens provide a breathtaking focal point for holiday movie marathons. They deliver a premium home theatre feel that rivals the local multiplex, without the need for a cinema ticket.

Audio performance is equally vital for modern home setups. Multi-room soundbars from premium brands like Sonos and Bose are in incredibly high demand, alongside kitchen and living room display hubs that keep households organised. In the smart speaker category, YouGov Electronics Research notes that Google Nest holds a strong position among UK adults. Personal audio is also seeing heavy interest, with many consumers planning to purchase high quality headphones or wireless earbuds during the holiday season to pair with their new entertainment systems.

Next Generation Gaming and Wearables

Interactive entertainment remains one of the strongest retail categories during the holidays. Gaming hardware sits right at the top of the list for pure gifting, where items are bought specifically as presents rather than personal upgrades. Research from YouGov Holiday Consumer Insights highlights that home consoles lead this trend. However, portable gaming is also enjoying a massive resurgence, with handheld PC consoles like the Steam Deck and ASUS ROG Ally gaining widespread popularity among gamers who want desktop performance on the go.

Buying timing is critical when it comes to high value gaming hardware. Forward planning is essential, with a large segment of console shoppers securing their purchases during November sales events rather than deferring their buying decisions until December.

Wearable technology follows a similar promotional pattern, with many smartwatch and fitness tracker purchases taking place before December begins. Premium devices from Samsung and Fitbit are particularly popular among those looking to track their health goals into the new year. Meanwhile, traditional digital cameras have maintained a surprisingly resilient hold on the holiday market as consumers look to capture high quality family memories on dedicated hardware.

Premium Kitchen Tech and Home Comforts

Beyond screen entertainment, the modern home relies heavily on clever, design led kitchen appliances. When it comes to culinary upgrades, built in technology from the BSH group is highly coveted. The iconic Neff Slide&Hide oven continues to be a dream addition for passionate home cooks, offering unparalleled access to the oven cavity when roasting the Christmas turkey. Meanwhile, Bosch’s sleek induction hobs and double ovens offer reliable, precision performance for the ultimate holiday feast.

For food storage and festive entertaining, statement refrigeration is key. Haier is leading the charge with their premium American style models. The Haier FD 90 Series 7 and the Cube Series 5 fridge freezers provide massive capacity wrapped in French door designs, ensuring plenty of space for everything from the main course to the chilled champagne.

The demand for high quality beverages at home continues to boost the kitchen category. Premium integrated bean to cup coffee machines offer a complete coffee shop experience without leaving the house. Those meticulously crafted by our partners at Miele, such as the stunning Miele CVA 7840 built in series, have become essential statement pieces for modern kitchens. Miele appliances are renowned for their exceptional build quality, intuitive brewing technology, and elegant design, making them a perfect centrepiece for any culinary space.

Personal care and practical home utilities round out the top festive categories. High end hair styling tools and interactive sonic toothbrushes have turned personal grooming into a premium gift sector. At the same time, practical comfort items are seeing significant demand. Heated electric throws offer efficient warmth during colder months, while self emptying robot vacuums take the hassle out of post party cleanup.

Final Outlook for the Christmas Season

As the holiday shopping period reaches its peak, British consumers are striking a clear balance between practical budgeting and a desire for home upgrades. By taking advantage of early November sales, using new digital discovery tools, and prioritising items that offer long term value, shoppers are making sure their festive spend goes as far as possible. Whether it is enjoying a fresh barista quality coffee from a Miele machine on Christmas morning, pulling a perfect roast from a Neff oven, or settling down for a movie night in front of an immersive TCL Mini LED screen, the technology chosen this season will continue to enhance daily life long after the decorations come down.

To read the published article by Rupert Cook, Marketing Director, please visit ERT Magazine

Tagged , , , , , , , , ,

Why pop-ups are becoming a permanent part of retail strategy

With social and online shopping taking a larger share of consumer spending, technology is increasingly becoming part of the retail experience and many well-known retailers are unable to maintain a competitive physical presence. It is undoubtedly becoming increasingly difficult, especially when overheads are increasing as they are. But despite many brands disappearing from Britain’s high streets, the appetite for pop-ups has never been stronger for many brands.

The significant growth in pop-ups and experiential retail goes hand in hand with rising digital competition. It is easy for online-only brands to get lost in the noise, but physical spaces offer a chance to stand out and reach new audiences. However, committing to a permanent retail location for some brands may be considered a risk, especially given rising costs, pop-ups offer the perfect cost effective alternative.

Pop-ups strike a balance: flexibility, visibility and engagement with lower overheads and far less risk. The appeal of pop-ups goes beyond cost and convenience. The most effective activations allow brands to create memorable experiences, gather valuable customer insight and build connections that last long after the doors close. They also offer flexibility on location, taking the experience regionally.

Experience as brand language

While physical stores continue to struggle in attracting shoppers, limited-time pop-ups that combine novelty with meaningful interactions can often draw consumers in droves. In fact, recent consumer research shows that 35% of UK shoppers visited a pop‑up store from an online brand and traveled to do so, making it a considered rather than impulse shopping trip.

While online shopping is a more transactional experience, a temporary space offers an opportunity for a two-way conversation between consumers and brands, immersing the consumer in the physical experience of the brand, rather than the familiar two dimensional digital experience the consumer has experienced up until this point. From the design of the space to the products and ‘wow’ moments, temporary environments become a platform for brand storytelling, with no limits and every element reinforcing the brand’s personality and values.

“The most effective activations combine creativity with commercial thinking, creating moments that are exciting and memorable for consumers while delivering insight and value for the brand.”

Daniel Todaro, CEO, Gekko Group

An in-person experience allows consumers to interact directly with a product, service or idea, creating a stronger emotional connection than a passive digital impression. This is particularly valuable for technology brands. As products become increasingly sophisticated, providing opportunities for hands-on interaction in a real-life environment can be a defining moment in the customer journey.

For those that offer services rather than tangible products, a pop-up can make innovation feel more accessible and relevant. The recent Gemini Nano Banana pop-up experience at Freight Island in Manchester, for example, allowed consumers to interact with the technology whilst at a lively World Cup screening venue, with a photobooth providing a tangible reminder of something that is otherwise incorporeal.

What is interesting about these experiences is not simply that they use new technology, but that the technology itself becomes part of the reason to visit. The physical environment provides a context in which consumers can experiment with something that might otherwise feel abstract or has been difficult to understand.

Pop-ups as retail intelligence

While raising awareness remains a key objective, pop-ups are increasingly being used as more than just marketing moments. They are becoming valuable testing environments for brands seeking to observe and understand their customers to make informed retail decisions.

Pop-up experiences allow brands to experiment with messaging and engagement, test new products and services, explore different approaches and do this in multiple locations, understanding better customer behaviour and gauge appetite for a more promotional or permanent physical presence. When planned with clear objectives, temporary spaces can provide real customer insight that can shape future campaigns, customer experiences and wider retail go to market strategies.

As well as gaining retail intelligence, brands can collect valuable customer data. In contrast to digital interactions, where consumers often part with their data begrudgingly in exchange for a discount, the memorable, one-off moments offered by pop-ups feel like a fairer trade. This makes consumers more receptive to ongoing communications – provided they are relevant, helpful and interesting – helping brands build new and stronger relationships based on mutual respect.

What makes a memorable pop-up?

While pop-ups can be an opportunity to sell products, when done well, go above and beyond. Gen Z and Millennials are 2–4 times more likely than Baby Boomers to visit a pop‑up, with 43% of younger shoppers citing a “unique or immersive experience” as a major draw, while exclusivity and limited‑edition items further increase the draw to the store, and increase footfall and buzz. Think about the choreographed lines that formed recently at Westfield for the various movie and make-up pop ups, offering unique and engaging experiences that go beyond the brand and offer tangible take-homes for visitors.

Online fashion brands such as ASOS have used temporary spaces to stage immersive events featuring curated fashion edits, brand collaborations and interactive activations. Access to limited-time exclusives and ‘you had to be there’ moments not only makes brands more memorable and helps consumers ‘put a face to the name’, but is also inherently more shareable.

One of the biggest advantages of experiential retail today is that the audience extends beyond those who attend in person. Consumers share their experiences online via social media, where views and engagement drive awareness and extend the lifespan and reach of an activation.

However, when activations are designed primarily around social content, they can often feel hollow or performative. The strongest experiences give people a genuine reason to engage, whether through exclusivity, interaction, entertainment or discovery. When a brand creates something worth experiencing, the social amplification follows naturally and never feels forced.

The most effective activations combine creativity with commercial thinking, creating moments that are exciting and memorable for consumers while delivering insight and value for the brand. They must have a clear purpose, firmly rooted in the brand’s wider objectives.

The future of temporary retail

The growing appetite for pop-ups certainly does not signal the end of permanent retail locations, but rather the maturation of the online market. Brands recognise that transactional interactions do not drive the differentiation and preference needed to cut through growing competition. Pop-ups are a popular solution because they can achieve multiple objectives simultaneously: they offer an opportunity to connect with consumers and raise awareness, while also providing vital insights needed to shape commercial direction. 

As the landscape remains unpredictable, pop-ups offer appealing flexibility, allowing brands to test the zeitgeist and engage with consumers with a reduced element of risk or financial commitment associated with that of a permanent store. For some brands, pop-ups are merely a stepping stone towards a long-term physical presence – a way to assess viability. For others, pop-ups can often become a permanent part of their retail strategy, deployed as and when needed to support brand-building, acquisition or retention initiatives, and activated as and when needed, or when the time feels right.

To read the published article by Daniel Todaro, CEO, Gekko Group, please visit CreativeBrief

Tagged , , , , , , , , , , , ,

How can you capitalise on the £9bn Back-to-School Market?

With parents facing financial squeezes and children influenced by social media, Rupert Cook explores how housewares retailers can win big on hydration, food-on-the-go, and durability.

The annual “Back to School” (BTS) window is a commercial juggernaut, firmly established as one of the most critical trading periods for UK retail outside of the Golden Quarter. Valued at between £8.82 billion and £9 billion ($11.44 billion USD) in 2024, the market is on a robust trajectory, with a projected compound annual growth rate (CAGR) of 4.14% leading up to 2035.

For housewares retailers, however, the challenge is breaking through the noise of uniform promotions and apparel lines to secure a slice of this massive spend. While the electronics segment commanded the largest market share by value in 2024 due to the rising necessity of digital learning tools, the shifting habits of the British household open up lucrative doors for the home and kitchen sectors, if retailers know where to steer their inventory.

The Food-on-the-Go Phenomenon

The daily school lunch has evolved far beyond a basic sandwich wrapped in clingfilm. Packed lunches are now a major lifestyle category, driven by a mix of nutritional awareness and economic shifts.

Data from early September 2025 highlights what can only be described as the “Lunchbox Spike.” As the autumn term commenced, grocery data revealed massive spending surges on packed lunch staples compared to the preceding fortnight:

  • Yogurt: Up 26%
  • Cheddar cheese: Up 24%
  • Sliced cooked meats: Up 17%

While grocery retailers naturally enjoy the immediate lift in food sales, it is housewares stockists who supply the hardware to make these lunches possible. Parents require high-quality, reliable vessels to store, protect, and cool these perishables.

Furthermore, when looking at what children actually want, the desire for high-end lifestyle products is undeniable. Consumer research tracking the most requested items by UK children and teenagers for the new term shows that functional housewares are competing directly with fashion:

Top Term-Time Requests by UK Youth:

  • New clothes: 43%
  • New stationery/notebooks: 35%
  • Branded schoolbags: 34%
  • Premium water bottles: 27%
  • Designer bags: 23%

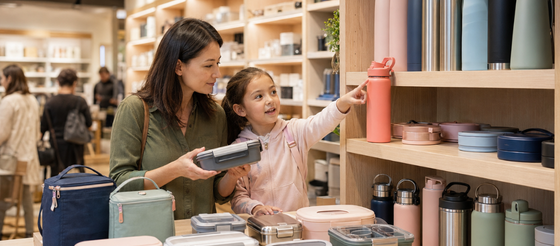
The fact that premium water bottles outrank designer bags and closely trail stationery is a massive indicator for housewares buyers. Hydration is no longer a utility; it is a status symbol on the school desk. The youth market has moved decisively away from basic plastic towards vacuum-insulated stainless steel, trend-led colourways, and innovative features like built-in straw lids and leak-proof seals.

The Budget vs ‘Pester Power’ Paradox

Navigating the upcoming BTS season requires an understanding of a clear consumer paradox: parents are feeling a severe financial squeeze, yet children are wielding more influence than ever over what gets bought.

On one side of the coin, the financial strain is stark. Parents reported an expected spend of £329 per child for the 2025 back-to-school season. For a fifth of families, this represented an average increase of £137, or a staggering 70% spike, compared to the previous year. Consequently, 56% of parents admitted to feeling intense pressure to spend beyond their means, with 28% relying on savings built up throughout the year to cover the costs.

This drive for value caused a notable shift in the clothing sector: while the overall childrenswear market dipped slightly over the summer of 2025, grocery retailers (such as Tesco, Asda, and Sainsbury’s) grew their BTS childrenswear sales by 8.4% due to convenience and value pricing. Similarly, 13.1% of schoolwear shoppers moved toward the circular economy, purchasing pre-worn uniform items through second-hand platforms like Vinted or community swaps.

On the other side of the coin sits the youth demographic. Over a third (36%) of UK parents claim that social media is driving their children’s demand for trendy new school essentials, with peer pressure and online influencers cited as the primary culprits.

Actionable Opportunities for Housewares Retailers

To capitalise on this £9 billion market, housewares retailers must position themselves as the solution to both sides of this paradox: offering the value and longevity that parents need, alongside the aesthetic appeal that children demand.

1. Implement a Tiered ‘Good-Better-Best’ Strategy

With over half of parents feeling the pinch, a solid foundation of value-driven, durable food prep containers is a must. However, given that 27% of children are actively demanding premium water bottles, retailers must not under-index on high-end stock. Ensure your inventory covers both entry-level utility and high-margin, brand-led hydration and lunchware solutions.

2. Capitalise on Content and Visual Merchandising

If 36% of demand is driven by TikTok and Instagram trends, your instore displays need to feel visual and “shareable.” Avoid sterile rows of plastic boxes. Instead, create colour-coordinated, lifestyle-focused “Fuel Station” displays that showcase matching sets of insulated lunch bags, bento boxes, and thermal flasks.

3. Sell the “Cost-Per-Use” Longevity Angle

Connect with the 13.1% of sustainability-minded consumers by marketing products on their durability. A parent under financial pressure may balk at a premium lunch flask initially, but clear signage highlighting that a stainless steel, impact-resistant thermal flask will last for years saving money on broken plastic replacements, changes the value proposition entirely.

4. Drive Cross-Category Bundles

Maximise transaction values by bundling complementary items. Pair lunch storage with small preparation gadgets (like mini food processors for making healthy snacks or egg cookers) to target parents who are actively meal-prepping to save money during the term-time rush.

Balancing the Basket

The back-to-school market is no longer a purely utilitarian exercise in buying trousers and pencils; it has transformed into a lifestyle-led retail event. By balancing value-driven durability with the aspirational products driven by social media, housewares retailers can secure an enviable and highly profitable share of this seasonal peak.

To read the published article by Rupert Cook, Marketing Director, please visit Housewares Magazine

Tagged , , , , , , , ,

What the World Cup Reveals About Effective Sales Promotions

Global sporting events have long represented some of the biggest opportunities in the marketing calendar and the recent World Cup has been no exception, generating huge audiences, heightened consumer spending and an influx of brand activity. But beyond the headlines, the biggest successes highlight how more brands are adding real value without the hefty spend associated with sponsorship deals and advertising.

Effective sales promotions were not built around the event itself, they are built around consumer behaviour. The brands that were performing best during the World Cup were not necessarily those with the biggest sponsorship deals, but those that understand how fans are watching, shopping, celebrating and sharing throughout the tournament.

Global sporting events still offer real commercial opportunity

According to a Bank of America report, the 2026 World Cup was set to be the biggest in history, with 75% of the world set to engage with the event in some way. The opportunity was not simply the size of the audience, but the opportunity to resonate with them by building promotions around real consumer moments and behaviours.

But adding football branding to existing campaigns will never get the job done. The most successful campaigns highlighted an important lesson for marketers: promotional activity only works when it is timely, relevant and gives fans a reason to engage, offering something genuinely useful, like Lidl’s £500,000 World Cup voucher giveaway, or creating a memorable and shareable photo opportunity, such as the giant World Cup trophy LEGO built from 1.3 million bricks.

England’s progress to the quarter finals was estimated to have generated a £500m boost for the UK economy, while Barclays reported spending increases across beer, pubs, clothing and online retail. The opportunity for brands wasn’t simply visibility, it was about understanding that consumers were already primed to spend, and setting up the most effective promotions to encourage it.

Global retailers responded in different ways. Here in the UK for example, Tesco supported England matchdays with free deliveries, football-themed merchandising and playful in-store touches like packaging redesigns to resemble footballs, recognising that consumers weren’t just watching football; they were shopping, hosting and celebrating around it.

The brands that recognised that consumers stocked up before kick-off, browsed their phones during breaks, celebrated wins with friends and were more willing to spend when emotion and occasion aligned are those scoring the goals.

Promotions are a worthy alternative

Beyond responsive campaigns, this year’s World Cup made it clear that brands do not need an official logo on the pitch or a multimillion-pound media budget to benefit from the tournament. While Fox Sports reportedly charged between $200,000 (£152,000) and $300,000 (£227,000) for a 30-second World Cup advertising slot, rising to around $750,000 (£567,000) during USA matches and the latter stages of the competition, many brands found more accessible ways to capitalise on heightened consumer demand.

This World Cup required non-partner branding to be concealed at tournament stadiums, and as the naming rights partners of two main fixture stadiums, Gillette and Levis both took this into their own hands. Levis masked the wordmark of its distinctive logo with a simple sheet, but its distinct batwing silhouette ensured it was still familiar. Similarly, Gillette covered its stadium branding in shaving foam, with both brands capitalising on the moment across their social channels, and owning the narrative. Among FIFA World Cup fans, Levi’s WOM Exposure rose from 17.4 on June 11 to 22.9 on July 12, while Gillette’s increased from 16.1 to 19.2.

Advertising can play an important role in driving growth, but it does not act alone. WARC notes that advertising is only one contributor to growth, with brand performance shaped by a much broader mix of commercial factors. Advertising still matters, but promotions often become the mechanism that converts awareness into action.

Investing in promotional mechanics is offering a more measurable route to commercial return than competing for expensive broadcast visibility. Instead, many retailers and challenger brands are focusing on these tactics to encourage immediate action. Loyalty offers, limited-time discounts, CRM campaigns and in-store activations allow brands to engage consumers in the moments they are already thinking about food, drink, gatherings and celebrations.

Meet audiences where they are

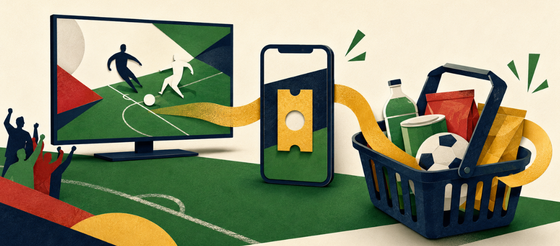
Leaning into today’s dual screen environment, mobile traffic data from Virgin Media O2 revealed increased smartphone activity during hydration breaks and half-time, reinforcing how naturally audiences now move between watching, scrolling and shopping. Reaching those audiences at exactly the right time is delivering dividends.

Rather than offering standalone discounts, the strongest campaigns integrated with the wider fan experience, rewarding existing customers, encouraging repeat purchases and creating reasons to engage throughout the tournament rather than only during the biggest fixtures. This resulted in worthwhile promotional activity that felt timely and relevant, while delivering clear commercial outcomes, highlighting how promotions can be used during global sporting events – with lessons that can be applied across BAU activity.

Relevance beats visibility

Any major sporting event generates a huge volume of marketing activity, and fans have come to expect that brands will inevitably participate, but generic campaigns can quickly blur into a sea of logos and noise. The most effective campaigns have stood out by interpreting the occasion in a way that still feels true to the brand.

Brands that have acted in the heat of the moment, driving conversation with clever social or activations, and made viewing occasions more than just a gathering with friends to watch the game are those that will earn lasting brand equity.

For example, in the final week of the tournament, UK supermarket Iceland’s decision to rename stores in England players’ hometowns landed well because it was simple, locally resonant and easy for consumers to engage with. The small-budget activity drove headlines while still feeling connected to the event.

During major sporting events, consumers are already shopping differently and the brands that connect marketing activity with those moments authentically are more likely to turn attention into measurable ROI.

Beyond the global pitch, how do marketers stay ready?

Any global event, whether sport or entertainment, creates the same temptation for brands to prioritise presence over purpose. But the biggest lesson from this World Cup is not that brands need to shout louder, it is that promotional activity performs best when it reflects how people actually experience the tournament.

Whether this was through retail offers, loyalty rewards, CRM, local activations or social campaigns, the strongest brands did not simply tap into football’s audience. They understood the moments that matter to consumers and built valuable promotions worth acting on, giving consumers surprise and delight moments that brought a tournament happening thousands of miles away to life.

To read the published article by Daniel Todaro, CEO, Gekko Group, please visit Advertising Week

Tagged , , , , , , , , , , , ,

Have human interactions become the new premium retail experience?

AI adoption for customer service is accelerating. Not only is it seen as a solution for making interactions faster and more efficient, but it is also seen as an investment to ultimately cut overheads in the face of increasing wage bills and tax burdens. The pace of transformation is so fast, in fact, that Gartner predicts Agentic AI will autonomously resolve 80% of common customer service issues without human intervention by 2029.

Just because we can, doesn’t mean we should – at least not until it can be embedded seamlessly into the customer experience. It’s not uncommon to have been frustrated by unintuitive, unhelpful chatbots and, despite 83% of consumers preferring to speak to a real person, the opportunities to do so are few and far between.

Consumers still exercise choice

To add insult to the injury of not being able to engage with customer service in the way they’d prefer, consumers are faced with poor quality AI interactions – and that’s costing businesses. A study from CEBR and Trustpilot revealed that poor experiences may have cost UK retail firms as much as £8.6bn in the previous 12 months, with two-thirds of consumers lessening their interactions with a business as a result of AI.

AI is also impacting the broader customer experience, with over two-thirds of consumers who have used AI when shopping unable to name a single experience that impressed them. Given the reliance on AI overviews, search and summaries, inaccurate information is likely the cause. Accurate tagging and product descriptions are critical for AI to do its job well, but many retailers aren’t monitoring and optimising their digital shelves effectively, which means experiences are falling flat.

While bad experiences put consumers off shopping with a retailer, the reverse is also true: great experiences are worth more. As consumers pursue experiences that meet their preferences, brands well-known for providing superior customer service are winning out.

It comes down to choice

Digital channels are not the only places where AI and technology are disrupting the retail journey. In-store retail experiences are being deprioritised, with on-the-ground headcount steadily falling as technology once again replaces the human touch.

Outside of the Black Friday rush, 75% of purchases are still made in-store, but omnichannel shopping is increasing. The growth of both webrooming – where consumers browse online before making a purchase in-store – and showrooming, where the opposite is true, highlights the need for consistently excellent experiences across channels.

When it comes to big-ticket items, many shoppers still prefer to go into store to see and feel a product, even if they then shop around for the best price. With technical specifications becoming more complicated, it is harder to understand which product best meets our needs, and – in addition to seeing a product in the flesh – many head to store to seek advice and reassurance, which means sales staff must be knowledgeable and, more importantly, available.

A lack of human interactions in store compounds any concerns about digital service. If you cannot engage with humans at any point in the purchase journey – from consideration to aftercare – how comfortable do you feel making a purchase with that brand?

Human experience is the new premium

It is vital that retailers continue to meet consumers’ expectations of their purchase experiences. High-quality service engenders trust and brand equity, with brand reputation and previous encounters also steering consideration. In the current operating environment, where gaining or maintaining share of market and achieving sales targets is already challenging, service standards should be a priority.

As AI interactions continue to disappoint and access to in-store support becomes limited, the human touch is becoming a rarity. Most consumers are prepared to pay more for better customer service, but being able to engage with real people – online and face-to-face – should not be limited to consumers willing to pay a premium. Ultimately, people buy from people they know, like and trust.

For retailers, this means balancing the financial benefits of transformation with customer centricity. Failing to deliver what your customers want can foster dissatisfaction. If your customers start to look elsewhere, no amount of cost-cutting can save you: as once trust is gone, it’s likely gone forever.

To read the published article by Daniel Todaro, CEO, Gekko Group, please visit Retail Sector

Tagged , , , , , , , , ,

Why experiential retail is the high street’s secret weapon

For years, the narrative surrounding the UK high street has been one of managed decline, overshadowed by the looming giants of e-commerce. However, for independent retailers whether you are demonstrating the latest smart home technology or showcasing bespoke homeware, the reality on the shop floor tells a very different story.

The modern consumer isn’t just looking to buy a product; they are looking to buy into an experience. Transitioning your physical store from a transactional space into an interactive, immersive environment is no longer just a marketing buzzword; it is a commercial imperative.

Here is how independent retailers can harness the power of experiential retail to drive footfall, foster loyalty, and protect their margins.

The Unwavering Demand for Independents

Before looking at how to change your store, it is vital to understand why you are in a prime position to win. The appetite for independent retail is robust. Recent data from The Industry Beauty (2026) reveals that over 80% of UK shoppers actually prefer independent retailers over large, faceless chains, particularly in considered purchase categories like homeware, gifting, and fashion.

This preference translates into regular footfall: 70% of UK consumers shop locally at least once a week, and regular customers typically return to the same independent business 11 times throughout the year.

What is driving this loyalty?

  • The Unique Factor: Over half (52%) of UK shoppers prefer the personalised and unique products found in small businesses over mass-produced items from larger chains.
  • Community Spirit: 51% of consumers want to shop small specifically to support their local community and economy.

Crucially, consumers are willing to put their money where their morals are. UK consumers have stated they are willing to spend up to £145 more per month on their local high street if the retail offering and overall in-store experience improve.

The Commercial Reality: Experience Over Price

It is incredibly tempting, especially during a cost-of-living squeeze, to slash prices to compete with online monoliths. However, racing to the bottom is a dangerous game for independents.

A stark 45% of retailers who are currently experiencing a decline in sales admit they have pivoted towards offering lower-priced products in an attempt to compete. This “discounting trap” often devalues the brand and squeezes already tight margins.

Conversely, despite broader economic pressures, an impressive 71% of UK independent retailers report that their trade is currently stable or growing. The differentiator is the in-store experience:

  • The Experience Uplift: Retailers who actively improve their in-store experience see a 13 percentage point uplift in their likelihood to achieve business growth.
  • The Power of Storytelling: Independent shops that invest in brand storytelling, communicating the ‘why’ behind their business and products are 19 percentage points more likely to report growth compared to those that do not.
  • The Human Touch: Direct, personal interaction in a physical store makes shoppers 60% more likely to make a purchase. You cannot replicate a passionate, expert product demonstration on a standard e-commerce checkout page.

Key Takeaway: Stop competing on price. Start competing on expertise, storytelling, and the quality of the customer’s time in your shop.

The Untapped Goldmine of Collaboration

You do not have to shoulder the burden of experiential retail entirely on your own. Teaming up with neighbouring businesses is one of the most effective, yet underutilised, strategies on the high street.

Consider the numbers: a massive 89% of independent retailers who collaborate with neighbouring businesses report a direct, positive commercial impact. Whether it’s an electrical retailer partnering with a local coffee roaster for an in-store barista tech demonstration, or a homeware shop hosting a joint late-night shopping event with a nearby fashion boutique, cross-pollination works.

Despite this extraordinarily high success rate, only 23% of independent retailers are actively collaborating today. However, 83% say they want to collaborate more. This highlights a massive, untapped opportunity for high street innovation. Reach out to the business next door; your shared customer base is waiting.

Pop-Ups, Tech, and the Appetite for Immersion

To secure the future of your business, you must look at how younger generations shop. Gen Z and Millennial shoppers are two to four times more likely than older generations to engage with pop-up retail environments in the UK.

For these demographics, the high street is an extension of their digital world.

  • Real-World Curiosity: 35% of UK online shoppers have visited a physical pop-up store launched by an online brand simply to get a real-world feel for the products.
  • The Draw of the Unique: 43% of younger shoppers state that a “unique or immersive experience” is a major draw for visiting physical stores over shopping online.
  • Social Media to Footfall: Online influence heavily drives physical footfall. A striking 60% of social media shoppers have visited a pop-up, compared to just 35% of traditional website shoppers.

Bridging the Physical-Digital Divide

Experiential retail doesn’t just mean a lovely window display; it means integrating technology that adds genuine value to the visit.

Over 50% of UK online shoppers have either used or want to use experiential tech features, such as Virtual Reality (VR) or Augmented Reality (AR), when shopping. Imagine allowing a customer to use AR on a tablet to see how a high-end coffee machine or a statement piece of furniture would look in their exact kitchen before they buy.

This isn’t just a gimmick. Seven out of ten shoppers who have used VR or AR in a retail setting describe the experience as engaging, helpful, or useful. By introducing smart retail tech, you bridge the gap between the convenience of digital and the tactile reassurance of physical retail.

Sensory Retail: Engaging Beyond the Visual

While technology like AR and VR offers cutting-edge visual engagement, true experiential retail appeals to all five senses. Independent retailers have a distinct advantage in crafting a multisensory environment that e-commerce simply cannot replicate a domain where you can truly outshine digital competitors.

Consider the ambient soundtrack of your store. Is it a generic radio station, or a carefully curated playlist that reflects your brand’s unique energy? Studies show that tempo and volume profoundly impact customer dwell time and purchasing behaviour. Similarly, the power of scent is frequently underutilised on the high street. Signature scents or welcoming aromas, such as freshly brewed coffee in a kitchenware shop or calming cedarwood in a menswear boutique can trigger powerful emotional responses, reduce shopping stress, and cement long-term brand memory.

Furthermore, actively encourage tactile interaction. E-commerce relies entirely on flat, two-dimensional cues, but physical retail allows customers to feel the reassuring weight of a handcrafted ceramic mug, trace the intricate weave of a sustainable fabric, or test the soothing texture of an organic skincare product. By intentionally moving products out from behind glass cabinets and directly into the hands of your shoppers, you instantly remove the physical barriers to purchase. When a customer can physically engage with an item while simultaneously absorbing complementary sights, sounds, and smells, its perceived value skyrockets, transforming a standard errand into a memorable sensory event.

Transforming Your Shop Floor

The data paints a clear picture: the UK consumer is highly receptive to independent retail, provided the experience justifies the trip.

To thrive in today’s trading landscape, independent retailers must view their premises not merely as stockrooms where transactions occur, but as interactive showrooms. Focus on your unique product knowledge, invest in face-to-face interactions, collaborate with your high street neighbours, and don’t be afraid to integrate immersive technology alongside engaging sensory design.

By creating a genuinely engaging environment, you give customers something the internet never can: a memorable, tactile, and thoroughly human experience.

To read the full published article by Rupert Cook, Marketing Director, please visit ERT Magazine

Tagged , , , , , , , , , , ,

Experts explain what you definitely shouldn’t buy on Amazon Prime Day

Millions of shoppers are expected to be hunting for bargains during this week’s Amazon Prime Day sales, but buying the wrong products could see consumers out of pocket. Research from retail consultancy Gekko found that whilst summer Prime day is the best sales event for televisions and smart fitness devices, other technology products drop to their lowest prices at different times of the year.

The analysis of hundreds of consumer technology products sold across the UK’s five biggest retailers during 2025 found that shoppers who understand when different categories are discounted will make the most savings overall. The analysis found that while summer Prime Day delivered the lowest prices of the year for televisions and smart fitness devices, shoppers looking for computer products, smart home technology and household appliances could often find better deals during different sales periods.

Smart fitness devices also reached their lowest prices during the summer event, averaging 7.5% below the annual average. October’s event paints a very different picture, with prices almost 10% above the annual average.

Don’t let ‘Deal Dazzle’ cost you hundreds of pounds

While Summer Prime Day offers genuine savings in some categories, the research found that consumers who assume that all Prime Day savings are unbeatable could be missing bigger bargains elsewhere. Computing products saw some of the biggest fluctuations throughout the year, with Easter promotions delivering prices 21% below the annual average – a discount of nearly £200 less than average and significantly cheaper than either Prime Day sale. Gaming products also proved better value during Easter promotions rather than the major Prime Day sales.

Shoppers looking for smart home and floorcare products will usually find the best deals in the week before Black Friday, while small domestic appliances are more expensive than average during all discounting moments, with November being the best time to buy.

The findings highlight what Gekko is calling ‘Deal Dazzle’, where the excitement around major retail events like Prime Day encourages shoppers to assume they’re getting the best prices of the year, without considering how discounts vary between product categories.

Daniel Todaro, CEO at Gekko, said: “Many shoppers assume major retail events such as Prime Day automatically offer the lowest prices of the year, but our analysis shows that’s not always the case. With household budgets continuing to face pressure, understanding when products are most likely to be discounted could help shoppers avoid paying more than necessary and make their money go further.

“Consumers should resist the temptation to assume a sale period automatically means the lowest available price. Taking a few minutes to compare prices and understand seasonal trends can make a meaningful difference to how much they ultimately spend.”

To read Gekko’s research and the published comment by Daniel Todaro, CEO, Gekko Group, please visit SomersetLive

Tagged , , , , , , , , ,

Resilience, Repairability, and the Rise of the ‘Quiet Premium’: Navigating the 2026 SDA Landscape

While the wider economic climate remains cautious, the UK’s Small Domestic Appliance (SDA) sector is proving that it’s more than just a ‘nice-to-have.’ With the market on track to reach £3.7 billion by the end of the decade, we look at the trends from Gen X spending power to the circular economy that are defining the retail winners of 2026.

The kitchen counter is currently the most hard-fought real estate in the British home. Following several years of volatile consumer confidence, the Small Domestic Appliance (SDA) market has emerged not just intact, but as a primary driver of retail growth. Valued at £2.8 billion in 2025, the sector is projected to climb toward £3.7 billion by 2030.

But for retailers, the “how” and “why” of purchasing has fundamentally shifted. As we move deeper into 2026, success is no longer about simply stocking the latest viral gadget; it’s about meeting a more disciplined, value-conscious, and tech-literate consumer.

The Demographic Tug-of-War

The digital transformation of the sector is undeniable, with 73% of UK SDA purchases now taking place online. This shift is spearheaded by the 16–34-year-old demographic, whose reliance on social commerce and peer reviews has turned “value-hunting” into a high-speed digital sport.

However, smart retailers are keeping a close eye on the “Quiet Powerhouses”: Generation X. While younger shoppers dominate the online traffic, those aged 45–60 are currently the highest-spending segment globally. This group is less likely to buy on impulse but far more likely to invest in premium upgrades high-end bean-to-cup coffee machines, cold press juicers, and professional-grade mixers even when their current appliances are still functioning. For this group, the “upgrade” is a lifestyle choice rather than a necessity.

Beyond the App: Innovation That Earns Its Keep

We have moved past the era of “smart for smart’s sake.” In 2026, consumers are looking for innovation that solves genuine pain points: energy costs and longevity.

  1. AI-Powered Maintenance: One of the most significant shifts is the move toward “self-healing” tech. Manufacturers are increasingly integrating AI diagnostics that alert users to maintenance needs before a breakdown occurs. This builds a level of trust that is essential for premium price points.
  2. The Urban Footprint: As single-person households and urban living increase, there is a surge in demand for compact, multi-functional design. Space is a premium commodity, and appliances that can air-fry, steam, and slow-cook within a single, sleek footprint are winning the battle for the countertop.
  3. The Connected Ritual: IoT is finding its home in ritualistic appliances. We are seeing high demand for smart water purifiers and coffee machines that don’t just “turn on” via an app, but utilise cloud computing to perfect and automate a user’s specific preferences.

The Circular Opportunity

Perhaps the biggest opening for UK retailers right now lies in the “Circular Economy.” Sustainability has moved from a marketing buzzword to a core purchase driver. Build quality and energy efficiency are now top-tier concerns for the UK shopper, largely driven by the long-tail effects of the energy crisis.

Retailers who offer trade-in programmes, refurbished lines, and crucially DIY repair options are finding a double-win: they appeal to the eco-conscious Gen Z while providing a budget-friendly entry point for price-sensitive households. Building a “repair over replace” narrative is no longer a threat to sales volume; it is a way to build lifelong brand loyalty.

Driving Growth in a “Deferred” Market

Data from the start of the year shows a clear trend: the UK consumer is becoming a master of the “wait and see.” Many are deliberately deferring big-ticket purchases until tactical promotional windows, such as January clearance or targeted spring campaigns.

For the physical high street, the challenge is clear. With footfall fluctuating, the store must become an “experience centre” rather than a warehouse. To protect margins and combat the threat of global supply chain shifts, there is a growing appetite for “Made in the UK” branding. Highlighting local manufacturing and robust build quality provides a sense of security that imported, unbranded alternatives cannot match.

The Bottom Line

The SDA market in 2026 is defined by a “flight to quality.” Whether it’s a Gen X shopper looking for a professional-grade morning espresso or a young renter looking for a repairable, multi-functional air fryer, the demand is there. Retailers who lean into experiential stores, transparent pricing, and the circular economy will find that while the consumer is more cautious, their appetite for genuine innovation is stronger than ever.

To read the full published article by Rupert Cook, Marketing Director, please visit Housewares Magazine

Tagged , , , , , , , , , , , ,

Navigating the Great Retro Revival

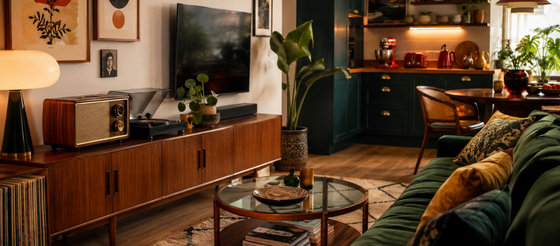
There was a time, not so long ago, when the “home of the future” was envisioned as a sterile, white-on-white laboratory. It was a world of hidden wires, touch-sensitive glass, and appliances that looked more like medical equipment than domestic companions. But walk into any stylish UK home in 2026, and you’ll find a very different story unfolding. The clinical minimalism that once dominated our Pinterest boards has been unceremoniously evicted, replaced by what design experts are calling “Eclectic Maximalism.”

For those of us in the electrical retail and trade sector, this isn’t just a shift in wallpaper choice. It is a fundamental pivot in how consumers view the hardware in their lives. Design is no longer a secondary consideration to be checked off after the spec sheet; for the modern consumer, design is the spec sheet. We are witnessing a “Retro Revival” that blends the warmth of the past with the intelligence of the future, and the opportunities for retailers are as vibrant as a cherry-red fridge.

Minimalism to Personality

The UK’s living rooms are currently undergoing a fascinating transformation. We are seeing a move away from the “buy it new, hide it away” mentality toward a more curated, character-rich aesthetic. The data tells a compelling story: the UK’s second-hand furniture market is on a trajectory to hit £1.1 billion by 2027. This represents a staggering 40.8% growth since 2022.

Why does this matter to the CE (Consumer Electronics) industry? Because the backdrop against which our products sit has changed. Consumers aren’t looking for a television or a speaker that blends into a white wall; they are looking for pieces that complement a “vintage maximalist” vibe, a search term that has spiked by 260% recently.

When a customer spends thousands on a mid-century sideboard or a refurbished 1970s velvet sofa, they don’t want a plastic-heavy, utilitarian piece of tech sitting on top of it. They want hardware that feels like furniture. This is the era of the “statement piece.” Retailers who understand this shift are no longer just selling gadgets; they are selling the finishing touch to an interior design dream.

Vinyl and Beyond

Nowhere is this nostalgia more evident than in the home entertainment sector. If you had told a tech analyst twenty years ago that in 2025, vinyl records would account for nearly 63% of all physical music sales, they would have laughed you out of the boardroom. And yet, here we are.

The UK vinyl market saw a massive 19.9% year-on-year increase in 2025, generating £174.7 million. This isn’t just a niche hobby for audiophiles anymore; it’s a mainstream cultural phenomenon. The tactile nature of physical media has returned with such force that even cassette tapes, a format many of us thought we’d left in the glovebox of a 1988 Ford Sierra, saw a 204.7% surge in early 2025.

But here is the most interesting part for the retail trade: 50% of people who bought a vinyl record in the UK last year did so as a collector’s or display item, without actually owning a record player. This highlights a critical insight: the aesthetic of the tech is often as valuable as its function.

However, for those who do want to listen, the demand for hardware is following suit. We’re seeing a boom in turntables and radios that look like they’ve been plucked from a 1950s diner but house high-fidelity internals. Take the radio market as a prime example. While analogue AM/FM listening has plummeted to 19%, DAB has become the titan of live radio, accounting for 48% of listening hours. The winning formula for retailers today is “Vintage Shell, Modern Soul” DAB radios with wood-grain finishes, tactile dials, and cloth speaker grilles that nonetheless offer seamless Bluetooth connectivity and crystal-clear digital reception.

The Kitchen Revamp

If the living room is the soul of the home, the kitchen is the heart, and currently, that heart is beating in full colour. For years, “safe” was synonymous with white or light grey cabinetry. Those days are over.

According to the latest Houzz UK Kitchen Trends Study, we are rapidly abandoning the clinical look. Grey still holds a lead at 21%, but blue (17%) and green (13%) are catching up fast. Interestingly, the UK has developed a particular love affair with green kitchens, leading the way in Europe. This shift toward deeper, more organic tones is creating a massive demand for appliances that can either contrast or complement these bold choices.

Enter the “Cherry Red” vibe. Identified as a major design trend for 2025 and 2026, this bold, retro-inspired shade is becoming the ultimate statement colour for small domestic appliances (SDAs). When a consumer invests in a kitchen renovation where the median spend has risen by 34% year-on-year, they aren’t looking for a £15 supermarket toaster. They are looking for the “cherry on top” of their £20,000 investment.

The SDA market is currently a powerhouse, valued at £2.8 billion in 2025 and forecast to hit £3.7 billion by 2030. This growth is being driven by design-led, multi-functional models. Consumers are looking for that perfect intersection of a retro silhouette, think rounded edges, chrome levers, and analogue temperature gauges and “smart” functionality.

The “Thrifty” High-End Consumer

One of the most surprising trends we’ve identified at Gekko is the rise of the second-hand kitchen. Much like the furniture market, there is a growing movement toward purchasing high-quality, pre-owned kitchen furniture. This is driven by a mix of sustainability concerns and a desire for “eclectic styling” that you simply can’t get from a flat-pack showroom.

For the electrical retailer, this presents a unique challenge and opportunity. A customer who has saved money by sourcing a high-end second-hand kitchen often has more “headroom” in their budget for premium, brand-new appliances. They want the vintage look of the cabinetry to be punctuated by the reliability and efficiency of modern technology. They are looking for the contrast of wood or laminate worktops (which hold a 14% market share) against the sleek, colourful pops of a retro-style kettle or a high-end range cooker.

Navigating the Retail Landscape

With 73% of UK consumers now choosing to purchase SDAs online to compare styles and prices, the role of the physical showroom has never been more vital or more pressured. To compete, the high street must lean into the “theatre” of the Retro Revival.

Online shopping is efficient, but it is rarely emotional. You cannot feel the weight of a chrome lever or see the way a “Cherry Red” finish catches the light on a digital screen. Retailers need to move away from “aisles of boxes” and toward “lifestyle vignettes.” Show the customer how that DAB radio looks on a mid-century sideboard; show them how the green cabinetry pops against a copper-trimmed toaster.

Final Thoughts

The “Retro Revival” is more than just a trend; it is a reaction. In an increasingly digital, intangible world, consumers are hungry for things they can touch, feel, and connect with. They want the reliability of 2026 technology, but they want it wrapped in the comfort and character of the past.

As we look toward 2027 and beyond, the winners in our industry will be those who recognise that we aren’t just selling “units.” We are selling the components of a home. Whether it’s a vinyl enthusiast looking for a deck that matches their “vintage maximalist” lounge, or a home cook looking for a stand mixer that serves as a piece of art on their green marble worktop, the message is clear:

Design isn’t just “everything”, it’s the only thing that makes a house feel like a home.

To read the full published article by Rupert Cook, Marketing Director, please visit ERT Magazine

Tagged , , , , , , , , , , , ,

Unlocking Online Growth

Time is something most business and running a website can feel like another major task. Yet in today’s connected world, it’s essential. Your website is at the heart of your brand, shaping customer perception and driving both online and in-store sales.

The UK is one of the world’s busiest e-commerce markets, with over 90 per cent of internet users shopping online. Online sales now account for 28.2 per cent of total retail, and this continues to grow.

Mobile is key, generating nearly 80 per cent of traffic and over half of purchases. If your site isn’t fast, clear and mobile-friendly, you risk losing customers.

Reducing day-to-day admin

Running a transactional website brings constant admin, from updating stock and prices to handling customer queries. For independent retailers, AI is becoming a powerful way to manage this workload.

Tasks like checking stock, writing product descriptions and answering routine emails can take hours each week, limiting time for business growth. AI tools such as automated stock management and chat assistants can reduce admin by 20-30 per cent, according to McKinsey & Company.

By working smarter, retailers can compete with larger chains. AI can generate product content instantly and handle common customer queries, freeing up staff to focus on higher-value tasks like customer relationships and sales. Another major time and profit product returns. Each return requires inspection, cleaning, repackaging and system updates, placing pressure on staff and resources.

In the UK, 71 per cent of online shoppers return items, with total returns expected to cost businesses £27 billion. To manage this, many retailers are rethinking their policies. Free returns are declining, with over 35 per cent of major fashion brands now charging, and 42 per cent of UK retailers applying return fees. This shift helps offset rising logistics costs and discourages excessive ordering, protecting already tight margins while reducing the operational burden of handling returns. For retailers with both physical stores and websites, creating a seamless experience is essential. Customers don’t see separate channels, just one journey with your brand. In fact, 83 per cent of UK consumers prefer a mix of online and in-store shopping, according to Bazaarvoice.

Click and Collect plays a key role in connecting the two. It allows customers to shop online and pick up in store, saving on delivery while increasing footfall. Importantly, it also drives additional sales, with 85 per cent of shoppers making extra purchases when collecting orders. Blending online convenience with in-store experience turns digital engagement into valuable in-person revenue.

Sustainability and shopper behaviour

Sustainability is becoming a growing influence on UK shoppers, and retailers can use this to drive both sales and cost savings. Simple prompts at checkout highlighting environmental benefits can shift behaviour, with Click and Collect rising to 71 per cent when carbon savings are shown, compared to 40 per cent without.

At the same time, a smooth checkout is critical. Basket abandonment is often caused by slow or complicated payment processes. Digital wallets are now widely used, with 57 per cent of UK adults relying on options like Apple Pay and Google Pay. Offering fast, one-click payments is no longer optional — it’s essential to secure sales from today’s convenience-driven shoppers.

If you are looking to find new chances online, you cannot ignore social media sales in 2026. Social media apps have moved fast from just being places to show off your brand to becoming very effective places to sell directly. Around 1.5 million UK businesses now use platforms like TikTok Shop, while 56 per cent of consumers have bought products through social apps — rising to 73 per cent among under-45s, according to Retail Economics.

This removes the gap between discovery and purchase, creating new revenue opportunities.

Ultimately, running a successful e-commerce business requires constant adaptation. By reducing admin with smart tools, simplifying payments, and connecting online, in-store and social channels, retailers can build websites that drive sales around the clock and keep pace with evolving customer expectations.

To read the full published article by Callum Puffett, Digital Marketing Manager, Gekko Group, please visit ERT Magazine

Tagged , , , , , , , , , ,